




Updated September 2026 by Moira Hayes, Finance / CFO & Member.
Your insurer decides the claim, not Robo Door. What Robo Door can do is give you paperwork that answers the questions insurers ask: an itemised quotation naming the product line, an invoice, an installation record and a warranty certificate under the Terms and Conditions of Sale. Keep those documents and confirm your policy's security requirements in writing before you order.
1. The policy asked for specific security and got something vaguer
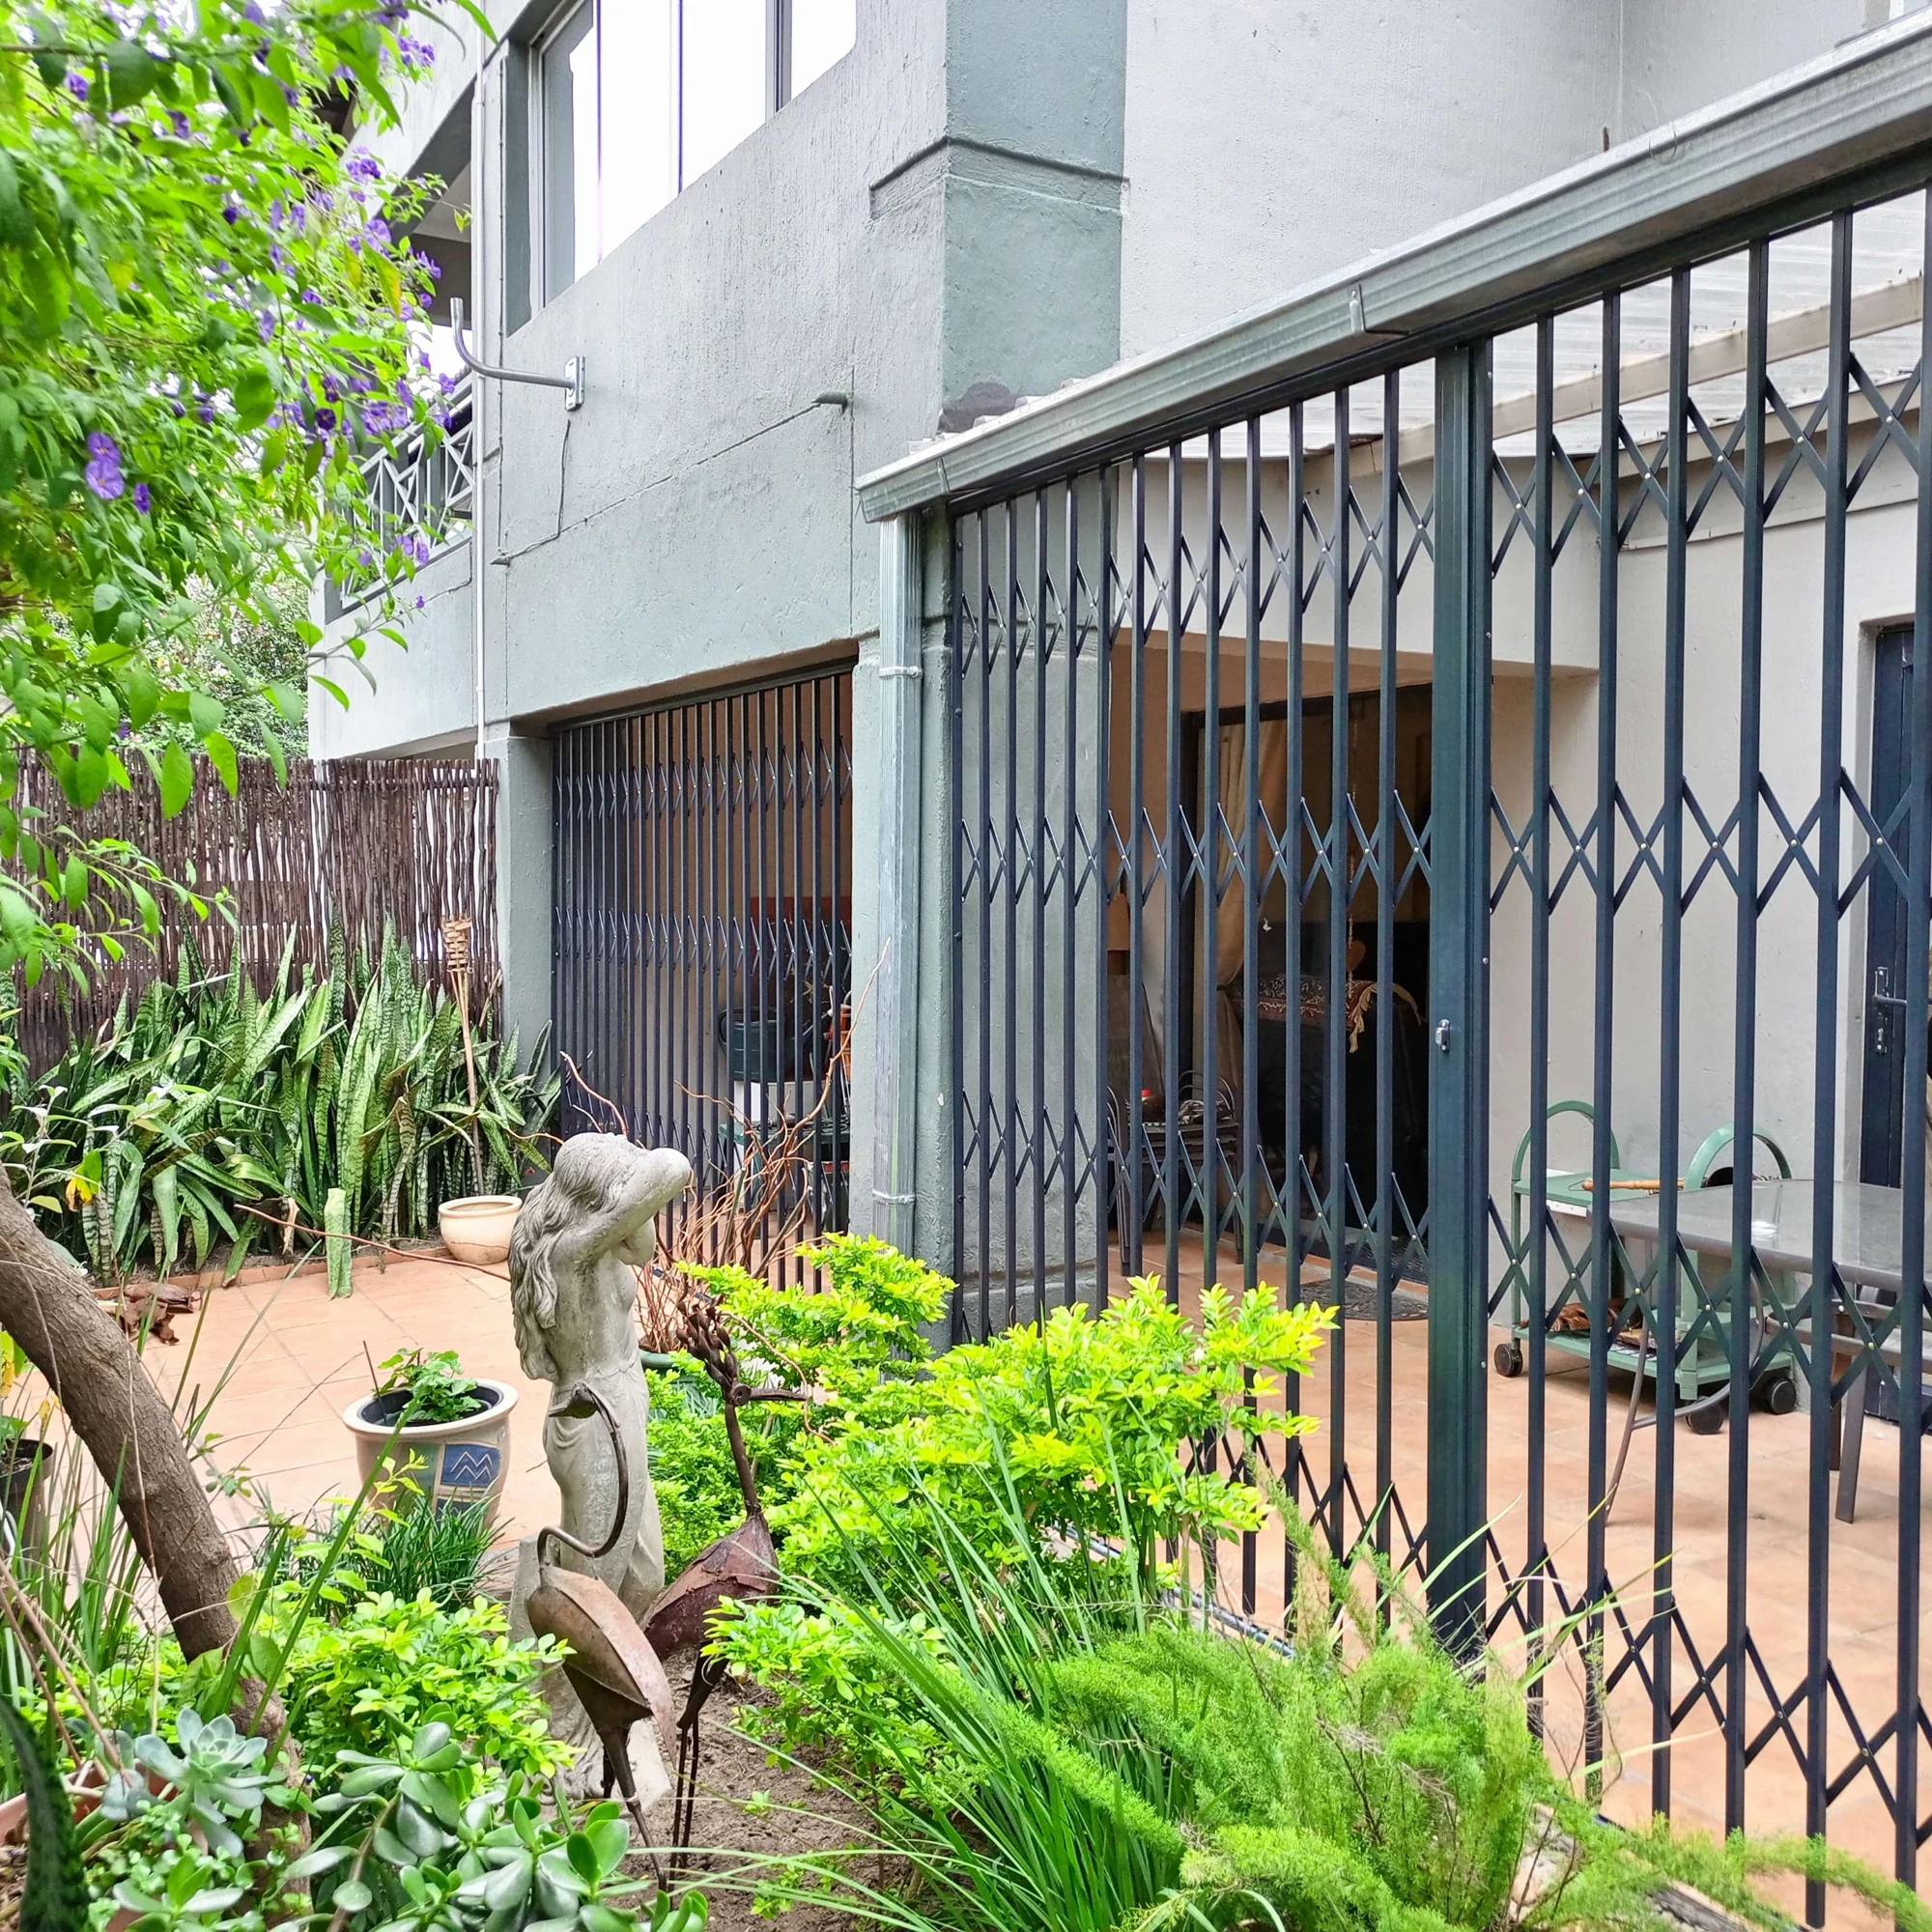
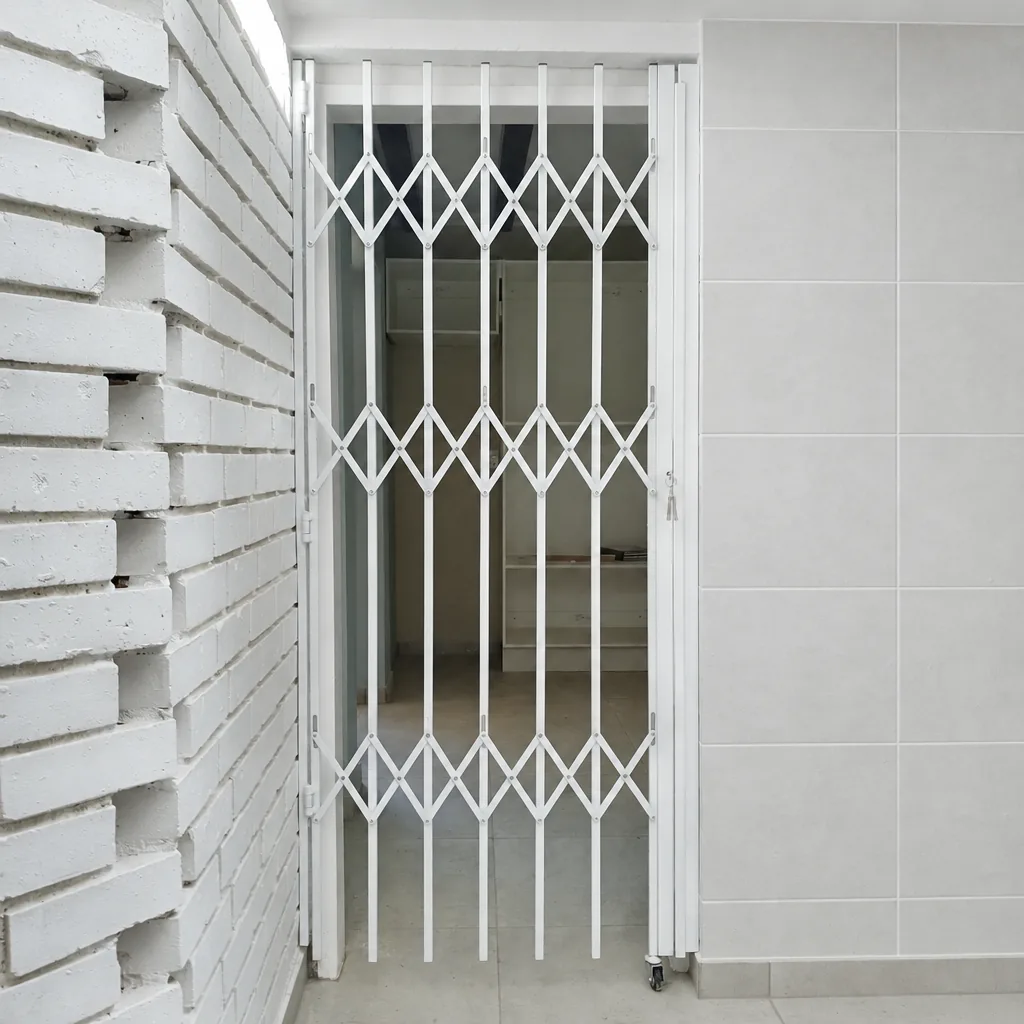
"Burglar bars" on a policy schedule is not a specification. Ask your broker which openings must be protected and whether a lock type, gate type or alarm is required. Put the answer in the quotation brief. A Robo Door quotation names the product line on every opening, for example Deluxe Fixture on the kitchen window and an Econo Trellis Door on the patio, so the schedule and the invoice match.
2. No proof of what was installed
Insurers ask for invoices, installation dates, photographs and product specifications. Keep the quotation, the invoice and the installation record together. Take your own photographs of each opening on the day of installation.
3. The security was not used
Many policies require gates to be locked and alarms armed when the property is unoccupied. A retractable trellis door left open on a hot night is, to an insurer, no door at all. Everyone in the household needs to know the locking routine.
4. The property changed and nobody told the insurer
Renovations, a new patio opening, a business run from home or a change of alarm company can all change the risk. Ask whether notification is required, and notify in writing.
5. Body corporate or estate approval was skipped
Scheme approval and insurance cover are separate questions. A trustee objection after installation can complicate a claim. Get written scheme approval first; see the sectional title article for the process.
6. Maintenance was neglected
A gate that no longer locks because the track was never cleared is a maintenance failure, and both insurers and warranties treat it as one. Our terms set the routine: wash twice a year, lubricate moving parts every six months, touch up chips within 30 days. Keep a note of when you did it.
7. The claim was disputed and handled informally
If a claim is refused, ask for the insurer's formal reasons in writing and use the complaints process and the ombud. For a material dispute, get advice from an insurance professional or attorney, not from a product supplier.
The pre-order checklist
- Security requirements from the insurer or broker, in writing
- Those requirements attached to the quotation brief
- Product line named on every opening in the quotation
- Invoice, installation record and warranty certificate filed
- Insurer notified after installation if the policy requires it
If you think a claim was refused unfairly, the Ombudsman for Short-term Insurance takes complaints about short-term insurers at no charge.
Next step
Send your insurer's security requirements with your enquiry and we will quote to them. Request a free quote, WhatsApp +27 82 888 1919 or call 082 888 1919.
Related
Reading
Read next


Get a free quote

Every opening priced in writing
A written quote with the warranty for each product line
Manufactured to suit your property and requirements
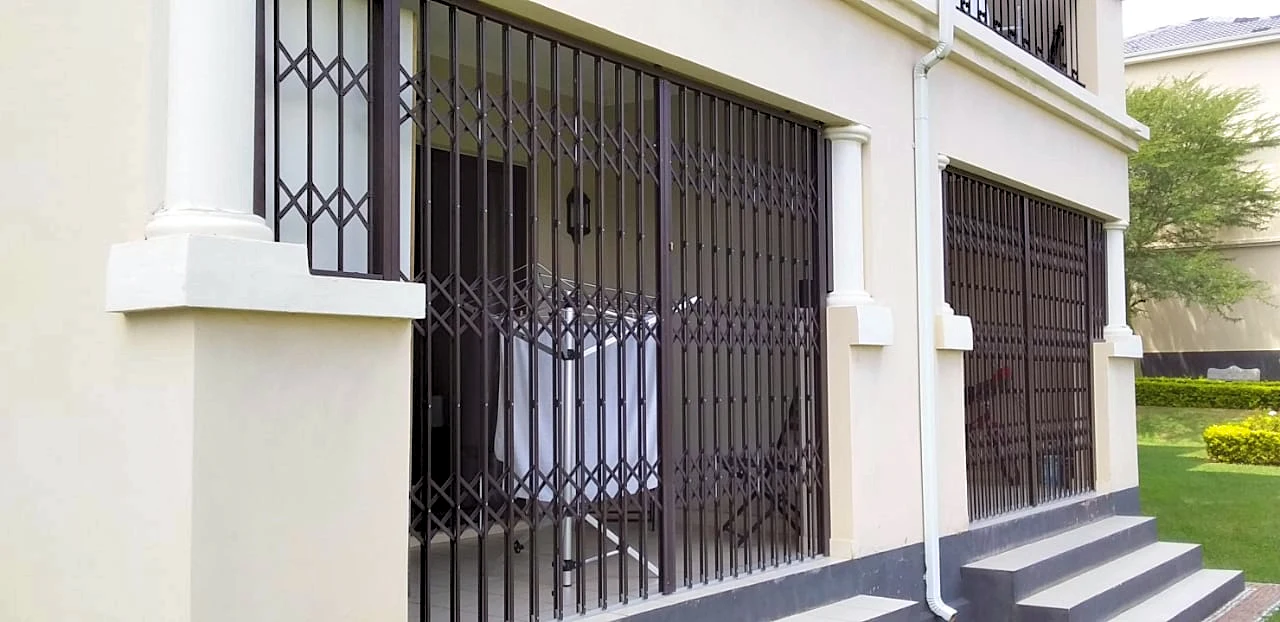
Custom-made burglar bars, gates and security doors, manufactured in our own factories in Alrode and Lusaka.
300,000+ products installed at over 49,564 properties since 2005
Coverage across 12 countries on the African continent
1,000+ reviews on Google, Facebook and HelloPeter